
Who it is for
Development finance due diligence on the site
The title, charges, ground, flood and planning evidence behind a loan, drafted for your credit committee.
In short
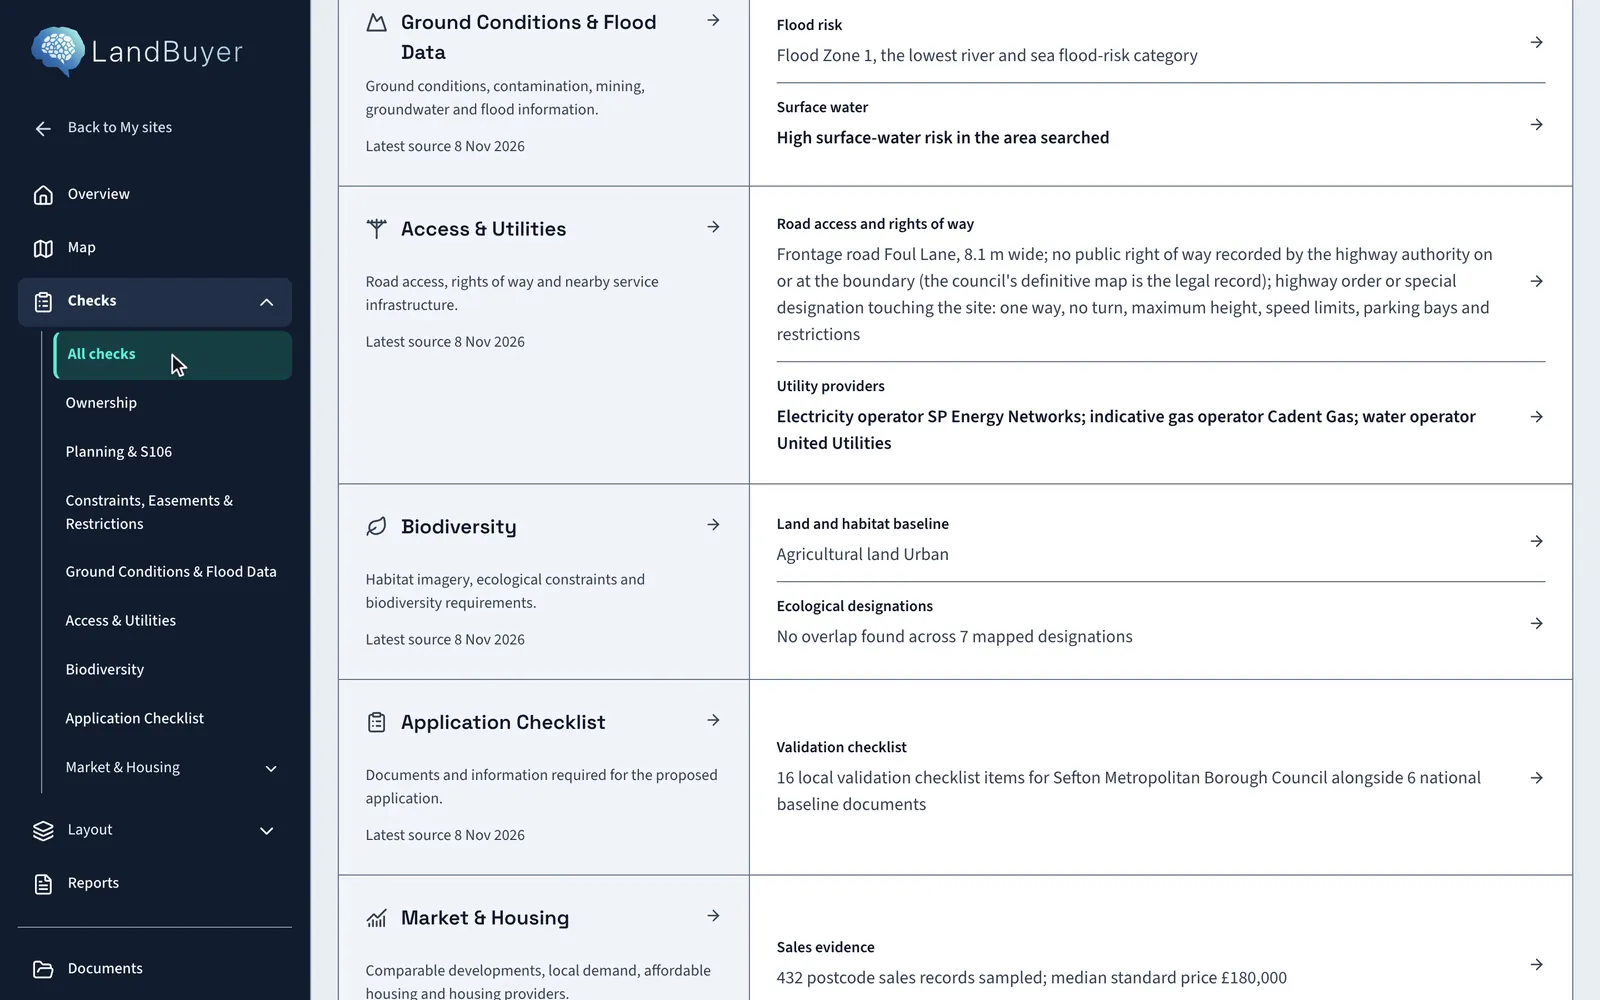
LandBuyer AI gives development lenders the site evidence behind a credit decision. It reads the title for restrictions and existing charges, checks ground, flood and planning, and states what each means for the loan. It drafts a lending evidence report and a credit summary for your credit committee, plus requisitions to the applicant.
The decision
Decide whether to lend, and on what conditions
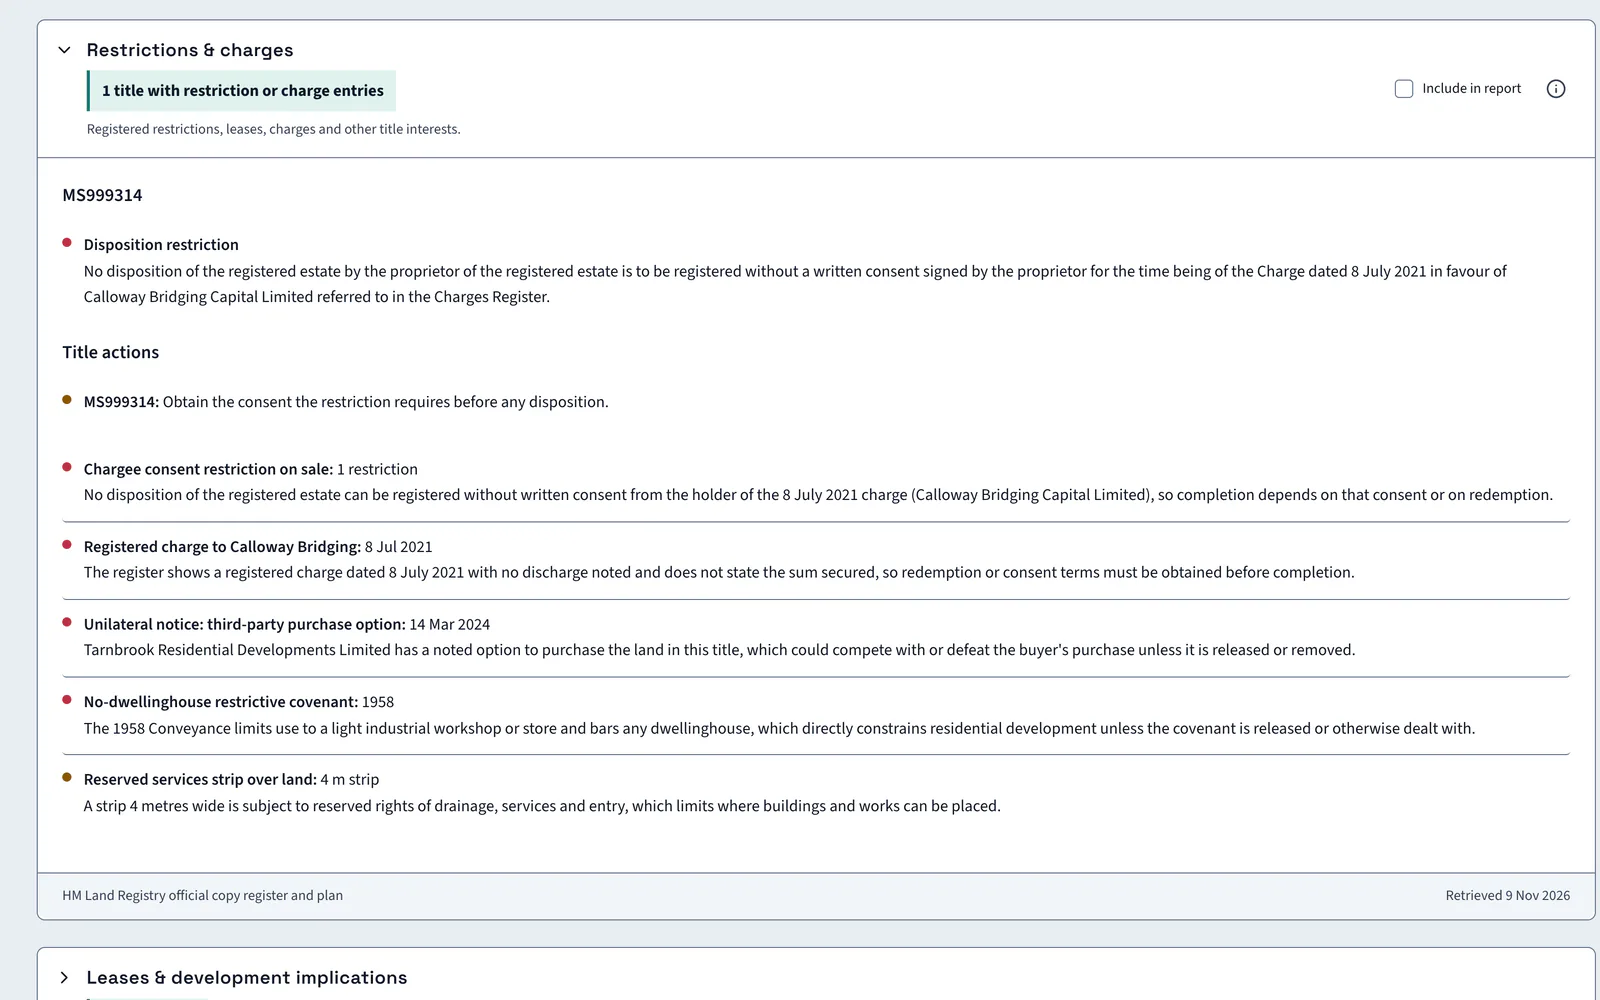
Your credit committee needs the security position and the site risks. On Kew Yard a charge from July 2021 must be redeemed, or its lender must consent, before any sale completes.
The checks that matter
Checks lenders rely on
-
Ownership
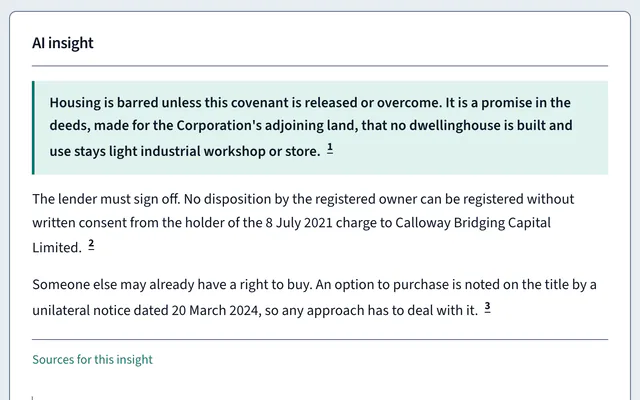
Existing charges and restrictions decide the security. Kew Yard has a lender consent restriction.
-
Geology
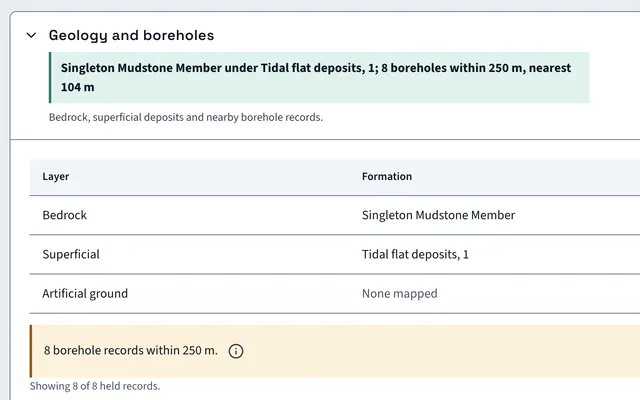
Ground risk affects cost and value. A ventilation shaft lies 178 m from the boundary.
-
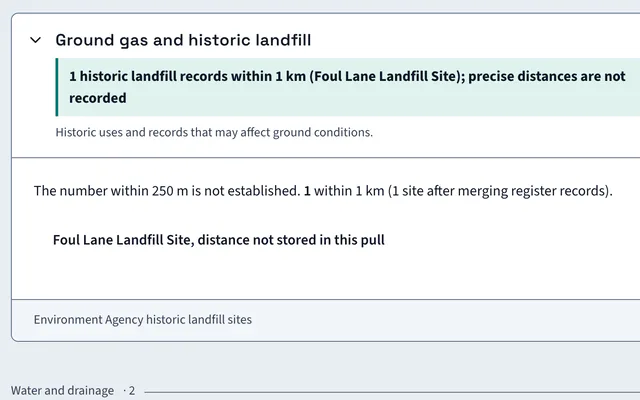
Ground conditions
Landfill and contamination are abnormal costs. One historic landfill lies within the search radius.
-
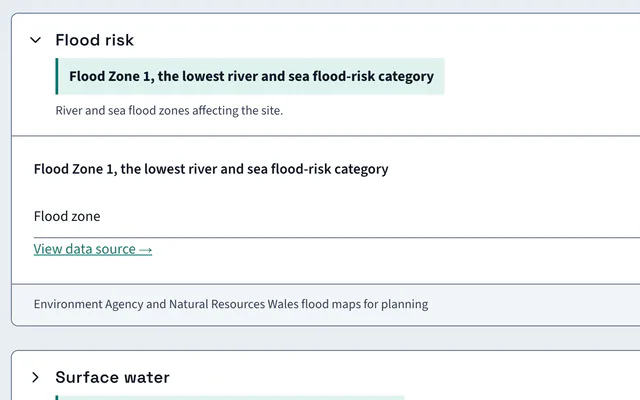
Flood data
Flood Zone 1, with high surface water risk in the area searched.
-
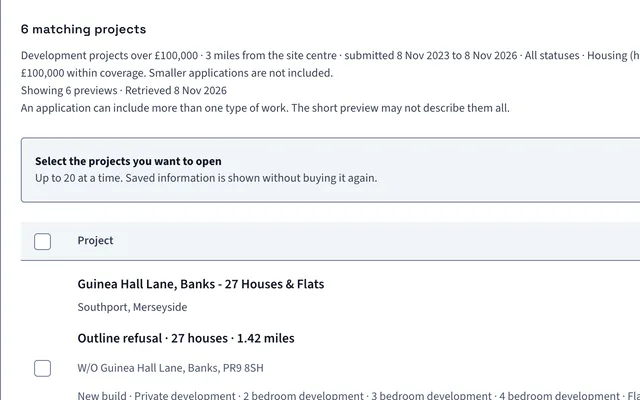
Planning
The planning position behind the exit. Four of five nearby applications were approved.
-
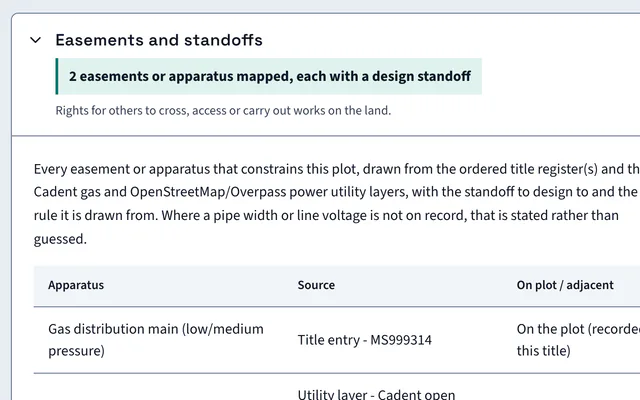
Easements and restrictions
A covenant barring dwellings and a 4 metre services strip affect the value of the security.
The report
The lending evidence report and credit summary
LandBuyer AI drafts a detailed lending evidence report and a short credit summary for your credit committee. The Kew Yard lending evidence report runs to 25 pages.
FAQ
Questions from lenders
Short answers to what land teams ask us before a demo.
Does LandBuyer AI show existing charges on the title?
Yes. It lists charges, restrictions and notices from the title register with the original wording. On Kew Yard a restriction needs the consent of the lender under a July 2021 charge.
Can it draft requisitions to the applicant?
Yes. Requisitions to the applicant is one of the reports it drafts, setting out the questions the evidence leaves open for the applicant and their solicitor.
Is there a lender setup?
Yes. Lender is one of the reader types set at onboarding, so the checks and reports are framed for a credit decision, with the security, the risks and the open questions set out first.
Can the credit summary go to committee on its own?
Yes. The credit summary is a short version of the lending evidence report for your credit committee, drafted from the same evidence. The Kew Yard summary runs to 9 pages, against 25 for the full report.
Keep exploring